
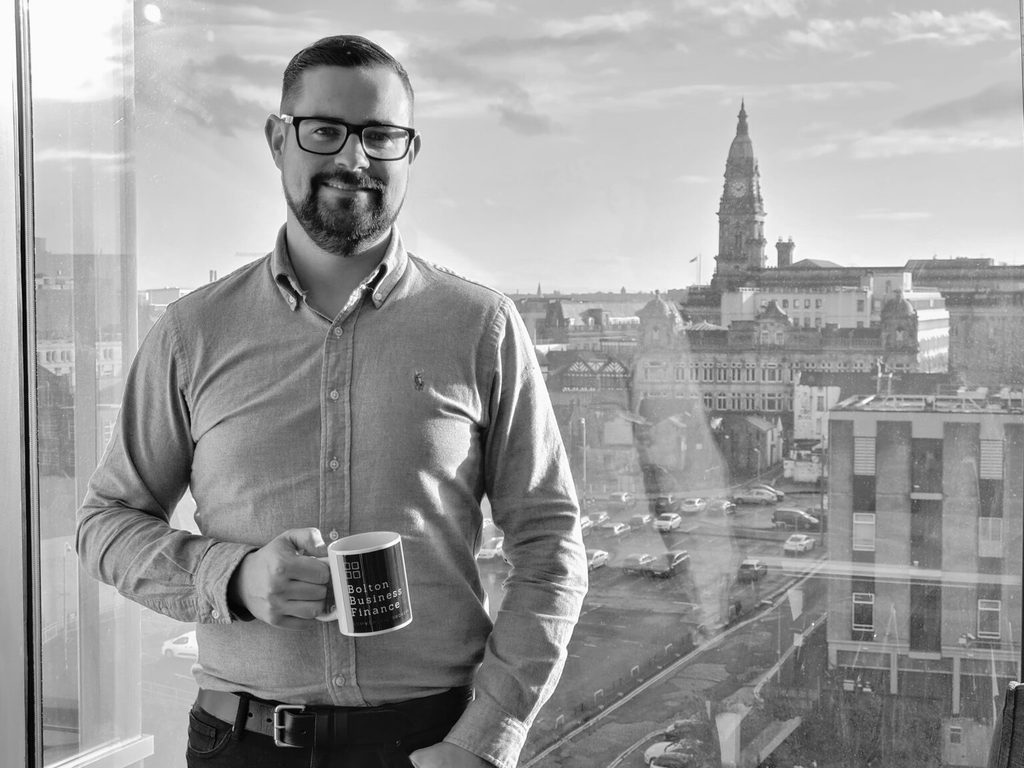
Founder and Managing Director, Bolton Business Finance Ltd. I have spent my whole working life around business lending, first inside a bank and now on the other side of the desk.
Background
I started in banking in September 2008 and have worked in financial services ever since. I began at Santander as a Bank Manager and later a Business Banking Manager, which gave me an early and close-up view of how lending decisions actually get made inside a bank, what underwriters look for, where deals stall, and how much difference a well-prepared application makes. That grounding still shapes how I work today.
I have also worked at Allianz, at AccessPay, and at Time Finance, a lender rather than a broker. Spending time on the funding side of the table is not a common background for a broker, and it is a useful one. Knowing how a credit paper is read, and what makes an underwriter uncomfortable before they can articulate why, is most of the job.
I moved into commercial finance broking in 2019 and founded Bolton Business Finance in March 2020, built around independent, whole-of-market advice with access to over 100 banks and lenders rather than being tied to a single lender’s products and appetite. Since then I have arranged over £20 million of commercial finance for UK businesses.
I am also a business owner and property investor in my own right, so I have sat on every side of a funding application rather than just one.
Qualifications and memberships
- BA (Hons) Business Administration
- Former Bank Manager and Business Banking Manager, Santander
- Previously Allianz, AccessPay and Time Finance
- Member of the National Association of Commercial Finance Brokers (NACFB), the UK’s principal trade body for commercial finance brokers; we adhere to its Code of Practice
- Eighteen years in financial services, from September 2008
Author
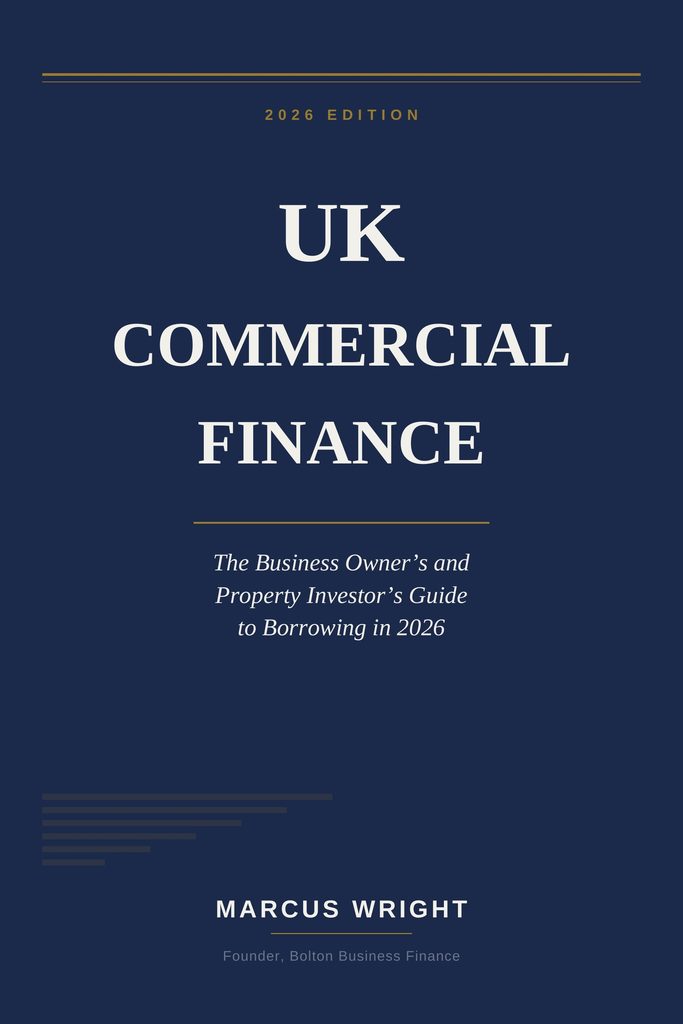
I have written a full guide to UK commercial finance, published in 2026. It covers the lending market, how decisions get made, how lenders view different sectors, and each of the main product types like unsecured and secured lending, invoice finance, asset finance, commercial mortgages, bridging and development finance.
I wrote it because the same questions came up in almost every initial conversation: what is the difference between secured and unsecured lending, will I need to give a personal guarantee, what does a lender actually look at. It seemed more useful to write an honest reference than to explain it from scratch on every call.
Writing and commentary
I write regularly about this market and am quoted reasonably often in the national and trade press on business lending, property finance and the wider economy. Journalists tend to call brokers when they want to know what is happening on the ground rather than what the official figures said six months ago.
Comments have appeared in the national press including The Times, the Daily Mail, the Daily Mirror, the Daily Express, Metro, the i and Business Insider; in the financial and property trade press including FTAdviser, Mortgage Solutions, Mortgage Strategy, Mortgage Finance Gazette, IFA Magazine, Financial Reporter, Professional Adviser, The Intermediary, Property Industry Eye and The Negotiator; and in business and regional titles including London Loves Business, Startups.co.uk, The Freelance Informer and Manchester World.
Those comments were given to journalists, in most cases through a press comment service connecting reporters with people working in the market. None of the publications listed has any involvement in this website, and none endorses it.
Why healthcare
Healthcare is an area of strong and specialised lender appetite that owners frequently assume will be difficult. Dental practices, veterinary practices, pharmacies, opticians and care providers all have dedicated lending teams at several banks, and terms can be markedly better than general commercial lending, sometimes with unusually high loan-to-value or advance percentages against goodwill, reflecting the sector’s low failure rates and regulated income.
What lenders examine closely is regulatory standing: your CQC, Care Inspectorate or RQIA rating and inspection history, registration status, occupancy, staffing ratios and the balance between local authority and private fee income. A recent poor inspection outcome affects your funding well before it affects your revenue.
Medical Business Finance exists to bring that specialist knowledge to one sector properly, rather than covering everything at surface level.
How I work
I still get personally involved in every deal we place. Whatever the product, the process follows the same five steps:
- Fact find: understanding the business, what funding is required and why
- Documents and information: gathering what lenders will need
- Quotation: going to market and comparing what comes back
- Application: submitting, packaging and managing the case
- Completion: through legals, valuation and drawdown
That can take a few days or a few months depending on the product and the complexity. Unsecured lending is usually quickest; property transactions take longest.
Get in touch
If you are considering a practice purchase, a premises decision or an equipment investment, I am happy to talk it through before you commit to anything.
- Telephone: 0161 546 9128
- Email: sales@bolton-finance.co.uk
- LinkedIn: linkedin.com/in/marcuswright87
See how we work or send an enquiry.